
Sellers Are Cutting Prices To Meet Buyers Where They're AtYou're scrolling through listings on your phone and everything looks good until you see the price (or the estimated monthly payment). Then

Dated: June 9 2025
Views: 4
If you’re a first-time homebuyer, you might feel like the odds are stacked against you in today’s market. But there are resources and programs out there that can help – if you know where to look. And one thing that can make homeownership easier to achieve? An FHA home loan.
They’re designed to help you overcome some of the biggest financial hurdles in the homebuying process – and that’s why so many first-timers are using them to make their purchase.
Whether you’re dreaming of ditching rent, planting roots, or just wanting a place that’s truly yours, an FHA home loan could be the path that gets you there sooner than you think.
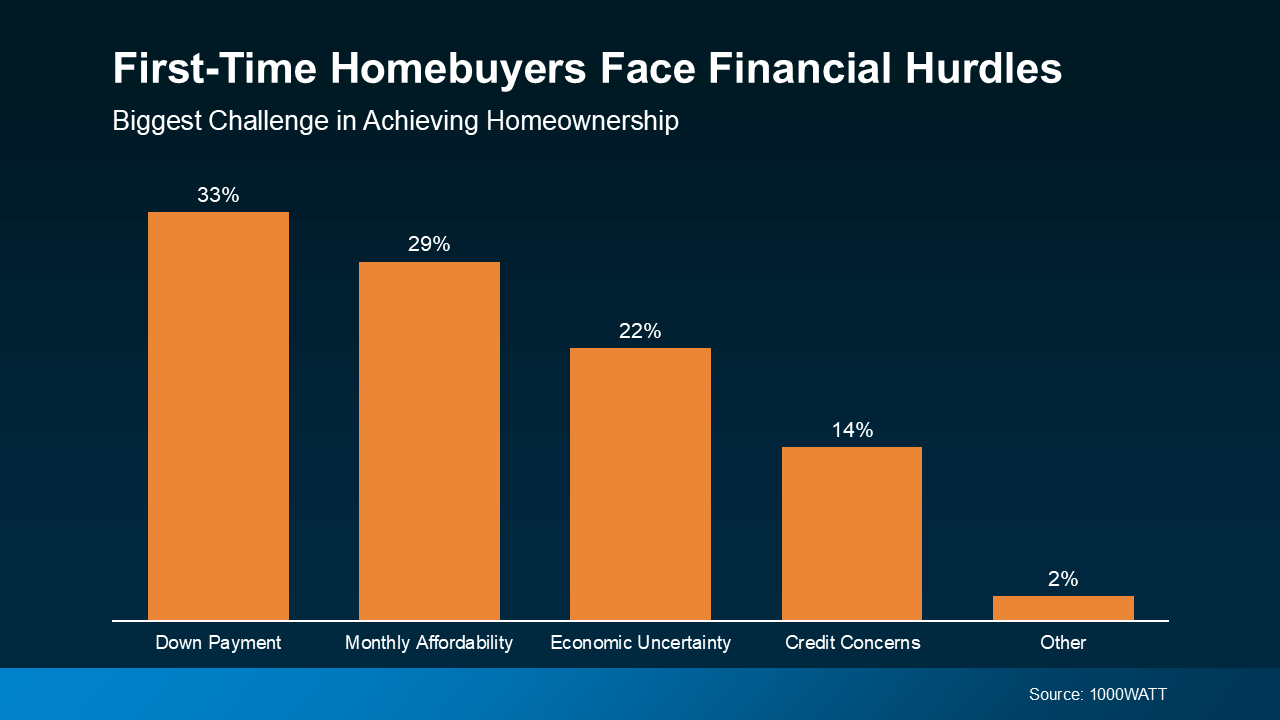
While the motivation to buy a home is still there for many people, affordability is a real challenge today. According to a survey from 1000WATT, potential first-time buyers say their top two concerns are saving enough for their down payment and making the monthly mortgage payments work at today’s home prices and mortgage rates (see graph below):
 That’s Where FHA Loans Come In
FHA loans help many first-time buyers overcome these challenges.
In fact, according to Intercontinental Exchange (ICE), the average first-time buyer using an FHA loan puts down just $16,000. That’s a big difference from the $77,000 they’re putting down with the typical conventional mortgage (see graph below):
 Essentially, buyers who use an FHA loan may not have to come up with as much cash up front. But the perks don’t stop there. You may also be able to pay less monthly, too.
That’s because, a lot of the time, the mortgage rate on FHA loans can be lower. Bankrate says:
“FHA loan rates are competitive with, and often slightly lower than, rates for conventional loans.”
So, if you’re thinking about buying your first place, an FHA loan may be worth exploring.
Because of the potential for lower down payment requirements and maybe even a lower mortgage rate, it could help with the two most common hurdles first-time buyers face today – saving enough money upfront and affording the monthly payment.
A trusted lender can walk you through the details, compare your options, and help you figure out what loan type makes the most sense for your situation.
With the right loan and the right guidance, homeownership may be more achievable than you think.
Do you want to talk more about your options? A trusted lender is there to help.
With 30+ years in the real estate industry, I've helped countless clients buy, sell and invest in homes. Each transaction is unique, with different needs, wants, timelines, and financial situations. T....
Sellers Are Cutting Prices To Meet Buyers Where They're AtYou're scrolling through listings on your phone and everything looks good until you see the price (or the estimated monthly payment). Then
Who Has the Upper Hand in Today's Housing Market?Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal. And just about every seller wants to know
The Case for Putting 20% Down on Your Next HomeIf you’re planning to buy your next home soon, you’ve probably heard the old rule about saving 20% for your down payment.The truth is, you
14 Years Running: Why Real Estate Is Still America’s Favorite InvestmentQuick gut reaction. Which investment do Americans trust more than stocks, gold, savings accounts, and bonds? The answer
 The data relating to real estate for sale on this website appears in part through the TREND Internet Data Exchange program, a voluntary cooperative exchange of
property listing data between licensed real estate brokerage firms in which The Move With Maura Team participates, and is provided by TREND through a licensing
agreement.
 © 2026 Florida Gulf Coast MLS (FGCMLS) Information deemed reliable, but not guaranteed. The IDX data relating to real estate for sale on this web site comes in part from the Florida Gulf Coast Multiple Listing Service. The information being provided is for consumers' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information is deemed reliable but not guaranteed.

The listing data displayed is deemed reliable but is not guaranteed accurate by CREA®. Data last updated on September 23, 2026 2:15 PM UTC The trademarks REALTOR®, REALTORS®; and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA®) and identify real estate professionals who are members of CREA®. Used under license. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by The Canadian Real Estate Association (CREA®) and identify the quality of services provided by real estate professionals who are members of CREA®. Used under license.
Show More...
 © BRIGHT, All Rights Reserved
Information Deemed Reliable But Not Guaranteed
The data relating to real estate for sale on this website appears in part through the BRIGHT Internet Data Exchange program, a voluntary cooperative exchange of
property listing data between licensed real estate brokerage firms in which
participates, and is provided by BRIGHT through a licensing agreement.
The information provided by this website is for the personal,
non-commercial use of consumers and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Data last updated: September 23, 2026 12:36 PM UTC
Some properties which appear for sale on this website may no longer be available
because they are under contract, have Closed or are no longer being offered for sale.
Some real estate firms do not participate in IDX and their listings do not appear on this website. Some properties listed with participating firms do not appear on this website at the request of the seller.
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than The Move With Maura Team may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 23, 2026 2:07 PM UTC
Show More...
